Credit Scoring Is Changing: 3 Things Homebuyers Should Know
Credit Scoring Is Changing: 3 Things Homebuyers Should Know
By David Torres | Broker Associate, Real Broker
Could the credit score you see on an app differ from the one a mortgage lender uses? Yes. And new options for mortgage credit scoring are being introduced, which can make the process confusing for buyers.
Here are three things to understand before you assume your score is too low—or that you’re already ready to apply.
1. A score you see online may not answer the mortgage question
Credit monitoring apps can help you keep an eye on your finances, but the score they show may use a different scoring model from the one used for a mortgage. Lenders also consider your credit report and other parts of your financial picture.
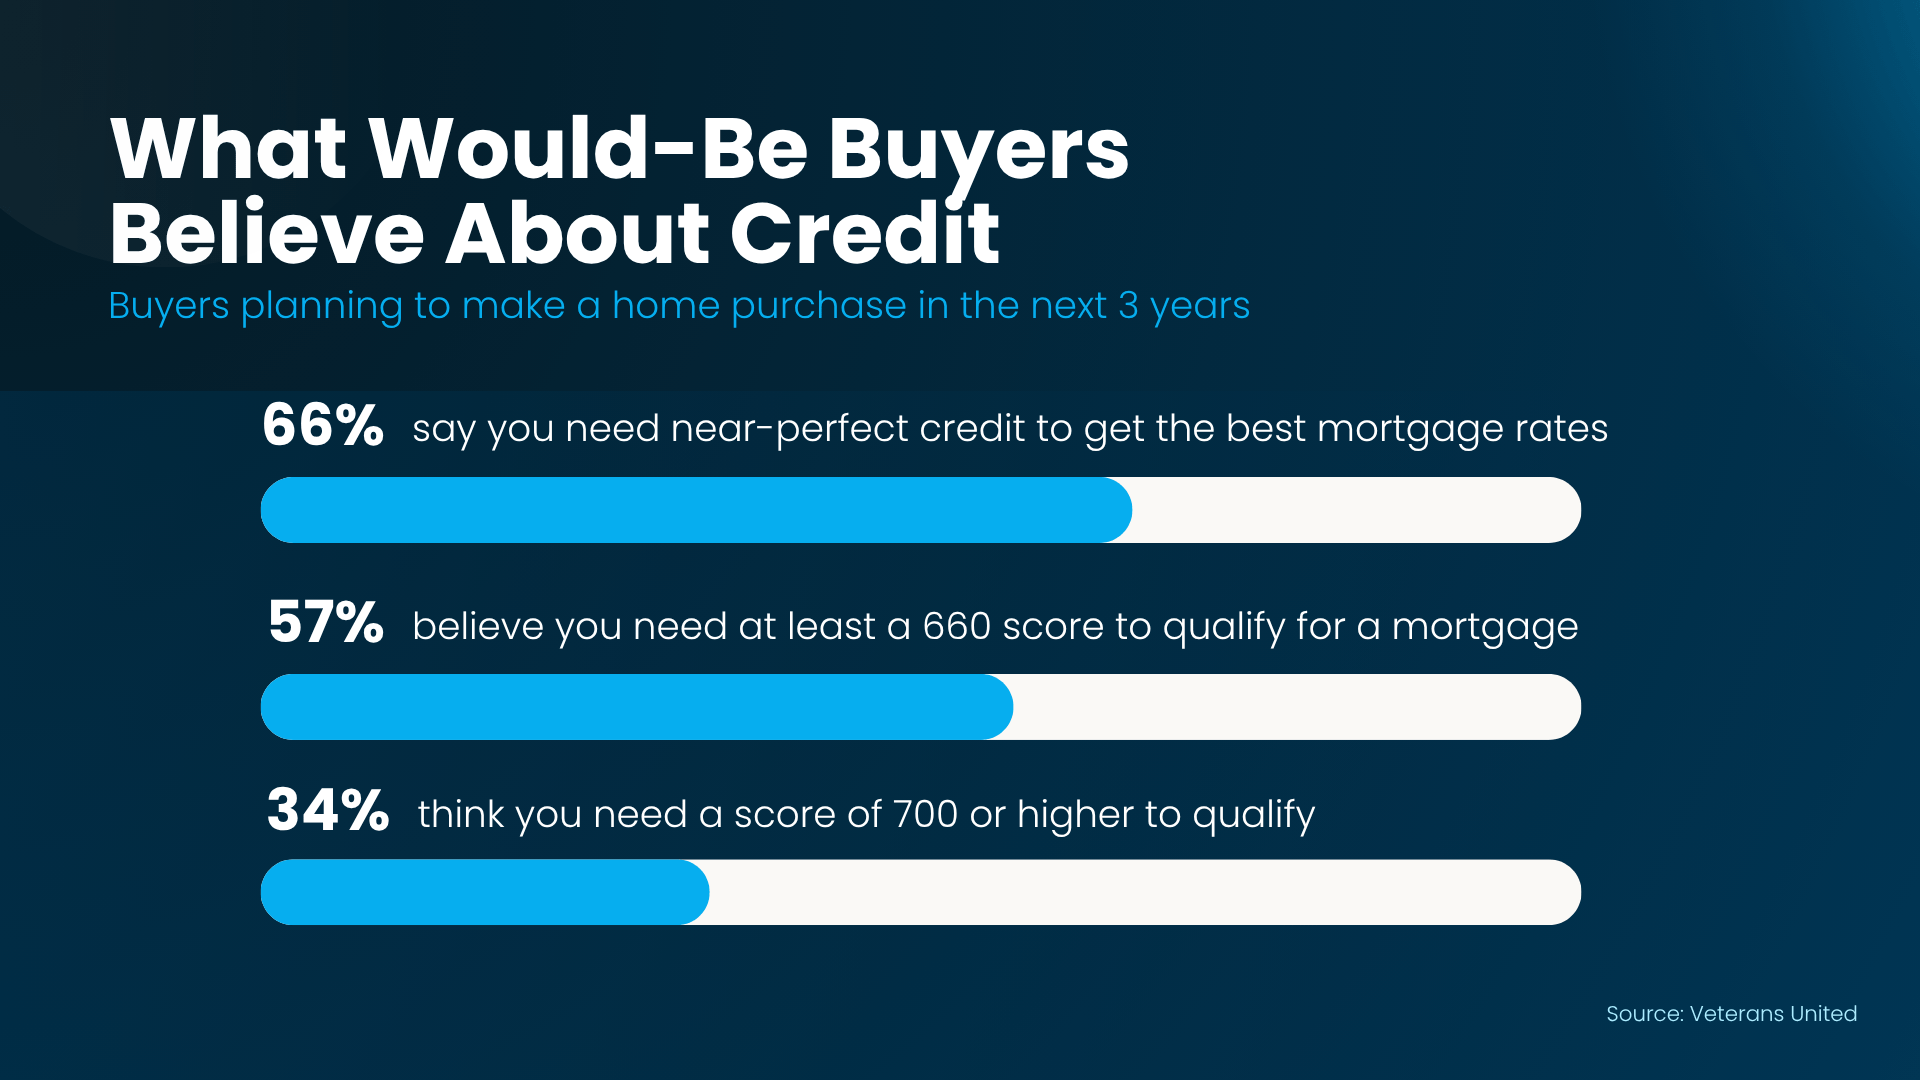
That matters because many consumers overestimate the minimum score needed to get a mortgage. In Fannie Mae’s 2023 consumer study, respondents’ median estimate was 652, while 620 was the then stated FICO minimum for certain loans sold to Fannie Mae and Freddie Mac. However, that figure is not a universal rule for every loan. Fannie Mae’s automated underwriting system, for example, does not require a minimum third-party credit score for its risk assessment.
2. Mortgage credit scoring is being updated
For years, mortgage lenders generally relied on Classic FICO scores for loans sold to Fannie Mae and Freddie Mac. That is changing. As of September 2026, approved lenders may use either Classic FICO or VantageScore 4.0 for eligible loans sold to those organizations. FICO 10T has been approved for future use, but it is not yet eligible for loan deliveries. FHFA
A different scoring model can produce a different number from the same credit history. So a score in an app—or one you checked several months ago—may not match the score used in your mortgage application.
3. Ask a loan officer for a plan based on your situation
The best next step is to have a qualified loan officer review your credit and explain which loan options may fit. They can tell you what score and documentation are relevant for the loan you’re considering, and whether there are steps you can take before applying.
In the meantime, stick with the basics: pay bills on time, keep balances manageable, and avoid opening or closing accounts without first asking your loan officer how it could affect your application.
[INSERT IMAGE: Credit checklist graphic | Alt text: Checklist of practical steps that may help someone maintain or improve their credit profile]
What this means for Lathrop homebuyers
If you’re thinking about buying in Lathrop or River Islands, don’t rule yourself out based only on a score from an app. A lender can review your specific circumstances, discuss possible loan programs, and help you understand what to work on before you begin your home search.
The right time to ask about your options is before you assume the answer.
Bottom Line
Mortgage credit scoring is evolving, and there isn’t one score that guarantees approval for every buyer or loan. Talk with a qualified loan officer to understand where you stand and what steps could help you prepare.
Looking to buy a home in Lathrop? I can help you plan your home search and connect you with a qualified local loan professional.
Start Your Home Search www.davidtorresjr.com
David Torres is a Broker Associate with Real Broker serving Lathrop, River Islands, and nearby communities. DRE 01944033.
Categories
Recent Posts